Industry Insights
AI Will Be Free. The Rails Won't.
By
Omer Rimoch
·

For the last decade, "what if rates go to zero?" was the standard objection to any fintech that earns on balances. I heard it in almost every fundraising meeting. It's worth answering properly, because the answer points to where AI is really going to make money.
Zero was the exception
The US ran near-zero rates twice: after 2008 and during Covid. Both were emergency responses. Neither was an equilibrium.
What's happening now is structural. The AI build-out is one of the largest capital programs in history. Hyperscalers are issuing bonds at a record pace, and that debt competes with a federal government running persistent deficits. When more borrowers chase the same savings, the price of money rises.
Economists call the resting rate "r-star." The New York Fed's estimate has climbed since early 2025, and market practitioners think the real number is higher still.
Rates will move up and down. Nobody can call the next meeting, and the Fed itself is split on 2027. But the floor has moved. A world where holding money earns nothing looks like the outlier, not the baseline.
AI is converging to free
On the other side of the ledger, intelligence is getting cheaper every quarter. Consumers already expect it for free.
ChatGPT has passed a billion weekly users, and the large majority don't pay. OpenAI's answer was ads. Google bundles AI into search. Meta gives its assistant away inside apps that billions of people already use.
Meta has run this play before. After Facebook bought WhatsApp, it removed the user subscription entirely. The money came from businesses paying to reach customers inside the chat. Now the same pattern is being applied to AI. Meta Business Agent is free for consumers to talk to. Businesses pay per token for agent replies, and paid business messaging is expanding from October.
Businesses will follow consumers. When a capable agent is bundled into the tools a company already uses, the standalone per-seat AI subscription gets hard to defend.
So where does the money go?
It goes to the rails.
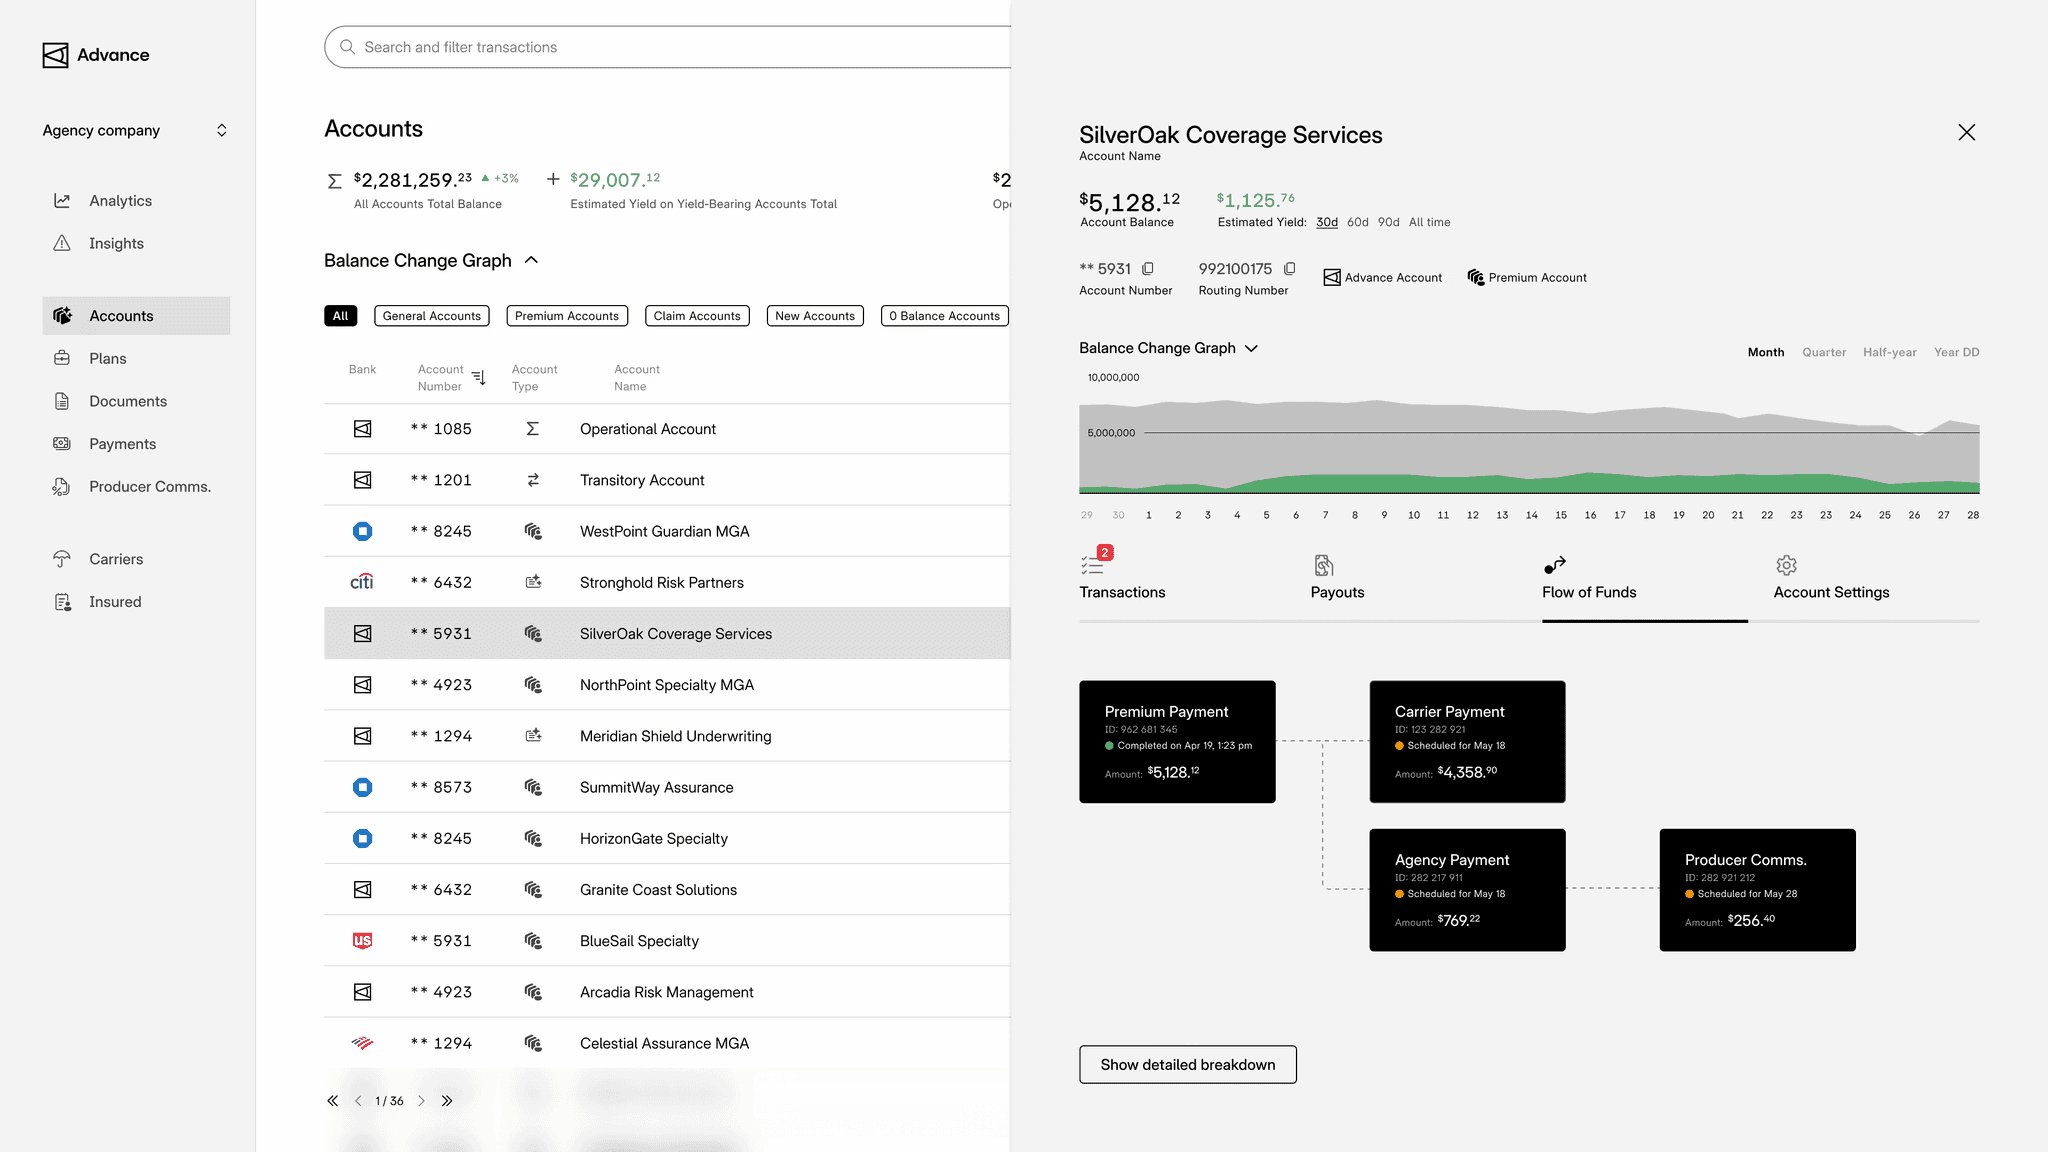
An agent that books a policy, pays an invoice, collects a premium or settles a claim creates a money movement. Every money movement has a ledger, custody, a settlement window and a reconciliation. Those layers earn a fee on the flow and a yield on the balance. They also own the relationship the money travels through, which is hard to replace.
The first attempt to put checkout inside a chatbot is instructive. OpenAI launched in-chat purchasing in late 2025 and pulled it back about five months later. Adoption stalled, and merchants kept checkout on their own infrastructure.
The lesson isn't that agentic commerce failed. The lesson is that AI companies own discovery, and the financial layer stays with whoever already holds the money, the trust and the compliance obligations.
Why rates make this a fintech story
In a zero-rate world, a platform holding customer funds earns nothing on them. It has to charge for software, and software is exactly what AI is commoditizing.
In a 4% world, the balance itself is revenue. A fintech that holds and moves money for an industry can give away the AI layer, subsidized by the float and the flow, and still run a better business than a company selling AI seats.
That's the asymmetry. AI-native companies need to charge for intelligence that is trending to free. Fintechs can give intelligence away because they get paid somewhere else.
The prediction
AI distribution won't be won by whoever has the best model. It will be won by whoever owns the account the money sits in when the agent acts. For consumers and businesses alike, AI will be free.
The rails won't be.
Sources
• Fed rate decision: federalreserve.gov – FOMC Statement, Sept 16, 2026
• 10-year Treasury yield: home.treasury.gov – Daily Treasury Par Yield Curve Rates
• NY Fed r-star estimate: newyorkfed.org – Measuring the Natural Rate of Interest (HLW/LW estimates)
• ChatGPT users / ads: openai.com – "Expanding access to AI" (Aug 31, 2026)
• Meta Business Agent pricing: developers.facebook.com – Meta Business Agent pricing updates
• OpenAI in-chat checkout: cnbc.com – "OpenAI's first try at agentic shopping stumbled" (Mar 20, 2026)
Disclosure
This post reflects the author's own analysis and opinions on market and industry trends. It is provided for informational purposes only and is not financial, investment, or tax advice. Advance is a financial technology company, not a bank. Banking services are provided by OMB Bank, Member FDIC.
Related posts