Industry Insights
Why MGAs are Leaving 3% on the Table
By
Team Advance
·
2 min read
The Math of Idle Capital
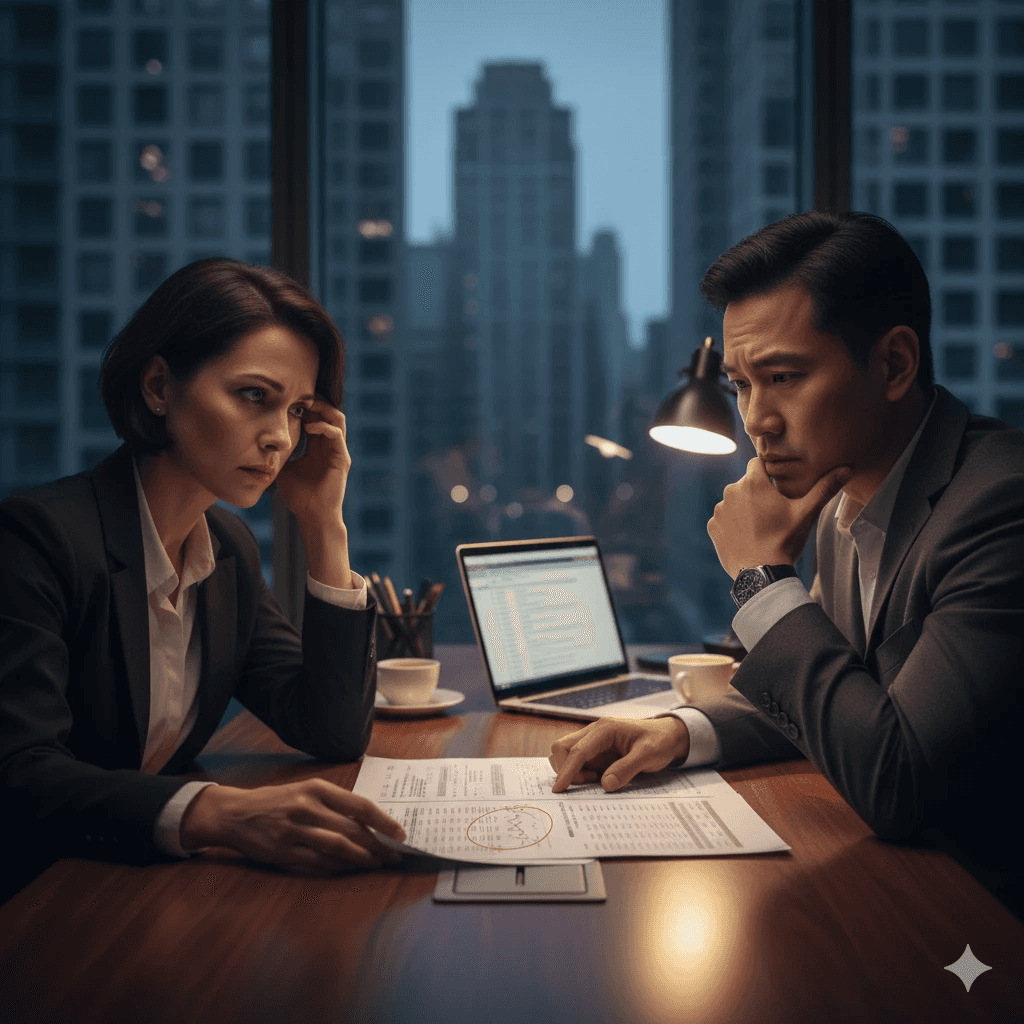
When you operate at scale, small percentages dictate the strength of your margins. As a hypothetical illustration, if your MGA maintains an average daily balance of $10M in fiduciary funds, leaving that money in a traditional bank earning 0% could mean giving up as much as $300,000 every single year, assuming Advance's rate of up to 3% APY* on that same eligible balance.
This isn't just "extra" money — this is revenue that covers your operational overhead, funds new hires, or offsets the cost of your entire technology stack. We call it "found money" because it requires zero change to your underlying insurance products or risk appetite.
Why Your Current Bank Won't Tell You This
Traditional banks aren't built to handle the complexities of insurance flow: the multi-party disbursements, carrier remittances, and strict fiduciary rules. Because they don't understand your workflow, they treat your deposits as static.
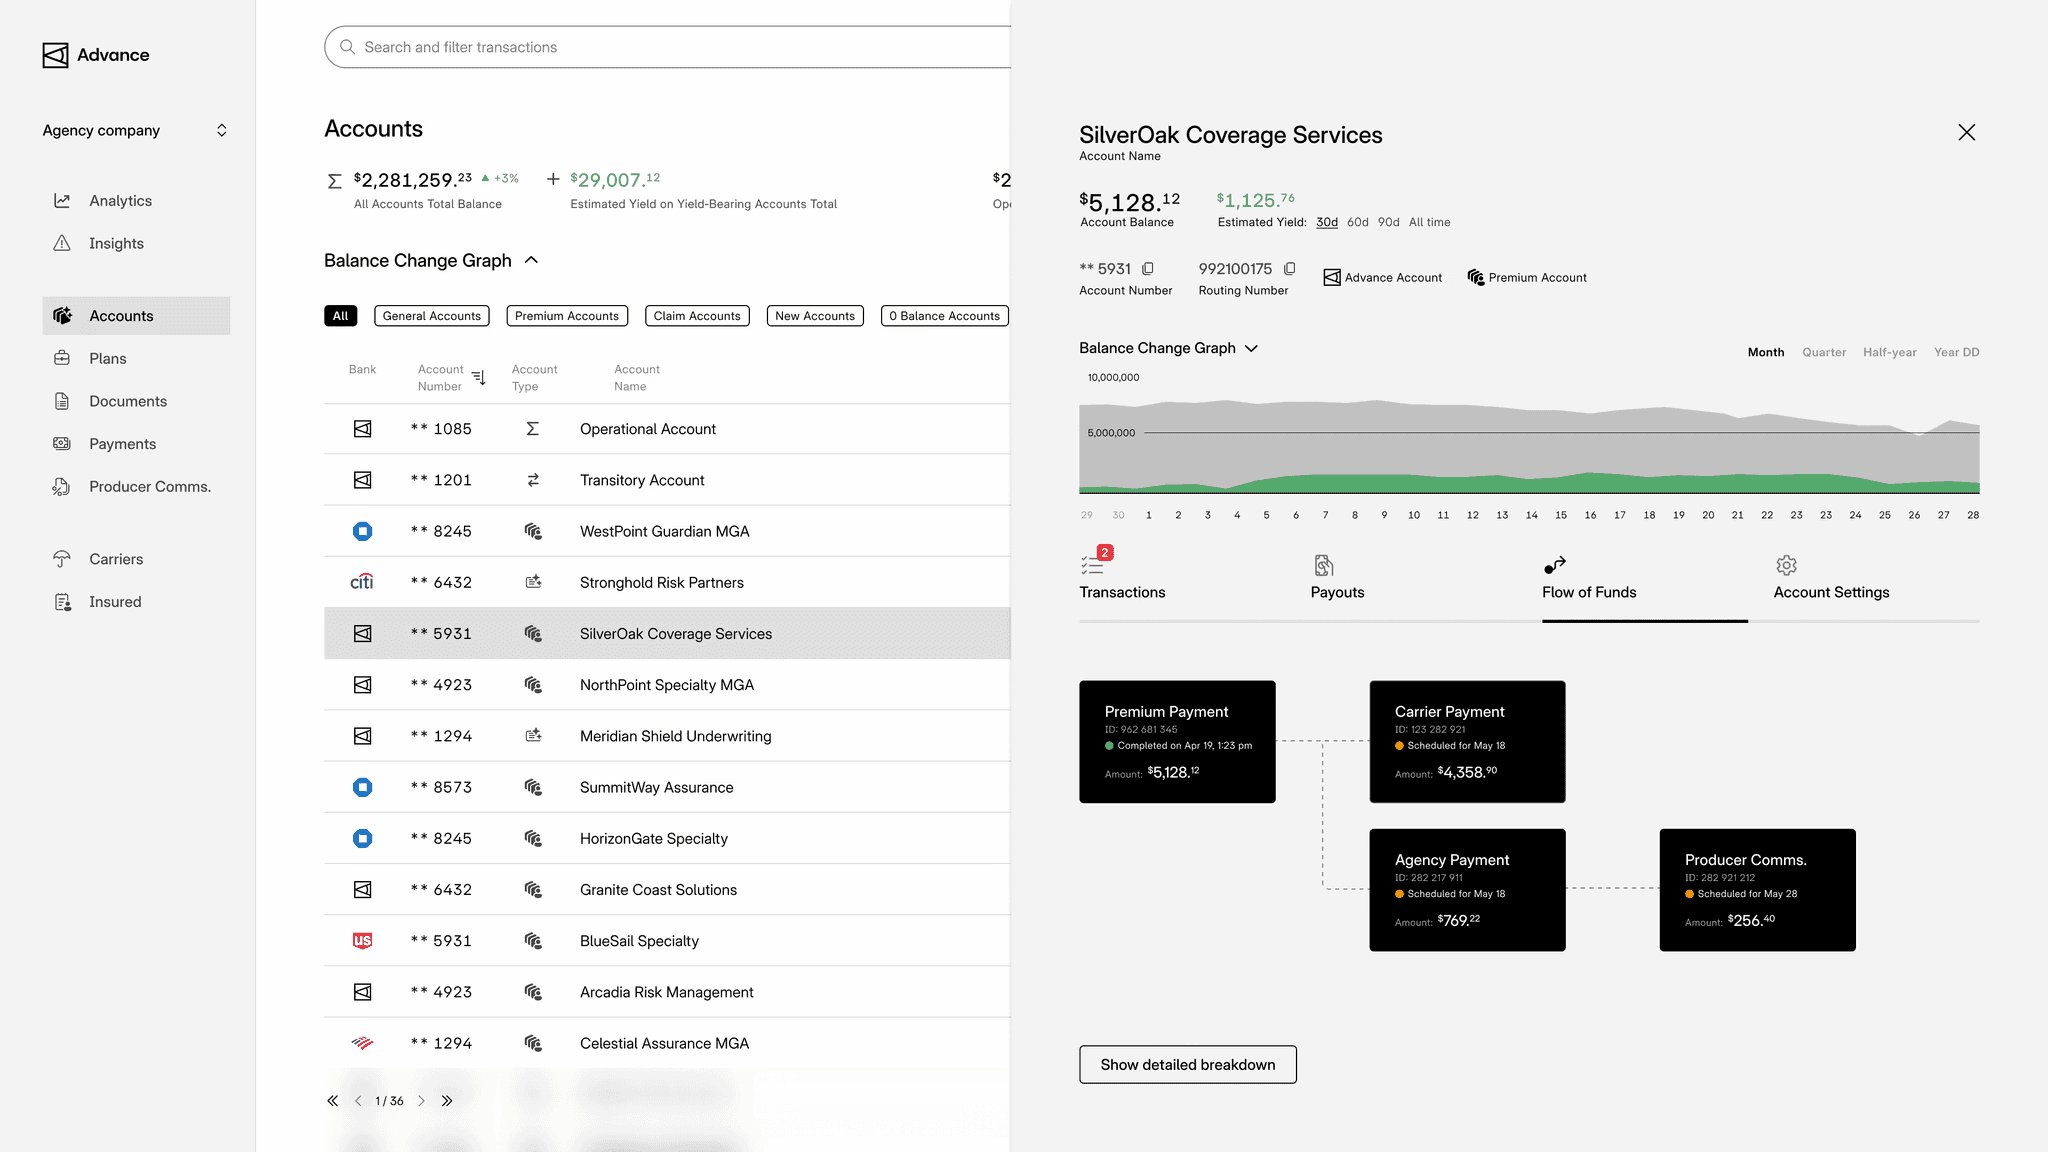
Advance is different. We built the technology layer purpose-made for how insurance premium actually moves, on top of banking services provided by OMB Bank, Member FDIC. We don't ask you to rip and replace your existing workflows or navigate complex AMS integrations. We simply provide the software that lets you capture yield you're already generating.
Stop Giving Away Your Float
Every week you wait to modernize your fiduciary infrastructure is a week of lost revenue. In an industry where margins are under constant pressure, ignoring a yield opportunity of up to 3% APY* isn't just a missed chance, it's an operational cost that compounds the longer it goes unaddressed.
In the time you read this article, you could have earned money.
Ready to stop the leak?
Related posts